

Cost plus method
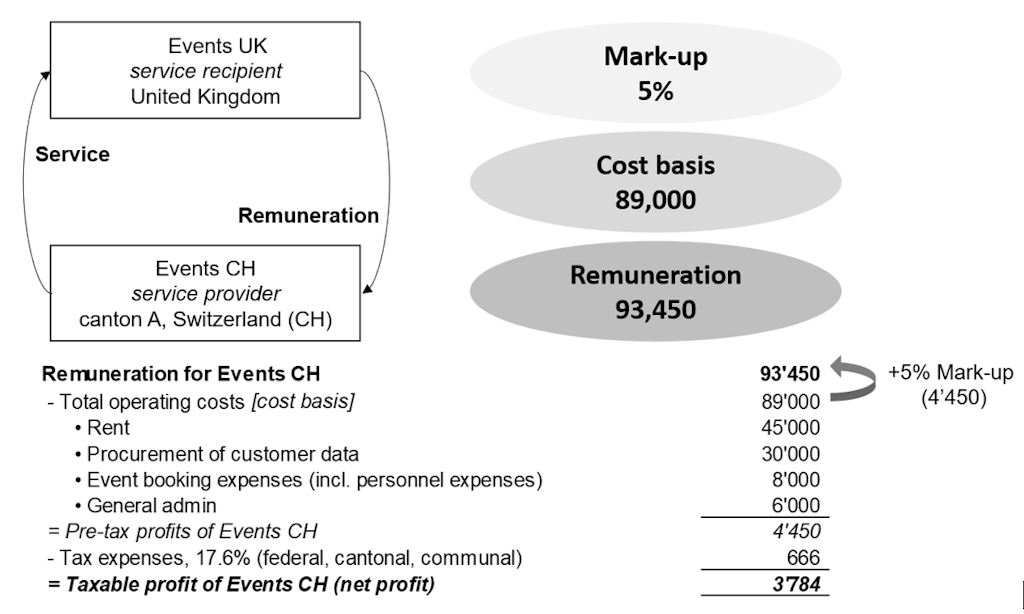
The cost plus method is based on the costs incurred by the provider of goods or services in an intra-group transaction. An arm’s length margin (mark-up) is then added to these costs, in order to achieve an appropriate profit. This method follows the basic principle that an enterprise strives to cover its costs while achieving a reasonable margin over the long term. The practical application of the cost plus method raises questions about the substantive and temporal cost basis on the one hand and the amount of the mark-up on the other.
Questions and answers on the cost plus method
Here you will find information on various transfer pricing topics in connection with cross-border transactions. This information is intended to provide clarification on selected issues. It is general in nature and cannot be used as the sole basis for the tax assessment of a specific fact pattern.
Contact
Please use the contact form for enquiries and to request a callback. If you would like us to call you back, please select the option ‘Would you like us to call you back?’ on the contact form and briefly describe your matter. Many thanks in advance.
Submit a ruling
To submit a transfer pricing ruling, please use the following email address: ruling.dvs@estv.admin.ch.
Federal Tax Administration FTA
Team Transfer Pricing
Eigerstrasse 65
3003 Berne